


Payroll management organizes the information, calculations, approvals and payments needed to pay employees correctly. It connects human resources, finance, managers and the payment provider. This article explains the operational controls that make payroll traceable and easier to review. It does not prescribe statutory rates or deadlines, which must be checked for the employer, employee and jurisdiction concerned.
Define the process and its boundaries
Identify which employees and employing entities the payroll process covers. Record the pay period, authorized sources of information and responsibilities. Different entities or employee groups may require different treatment. Do not assume that a setting copied from another payroll is suitable for your organization.
Separate the employment record, the payroll calculation and the payment instruction. The employment record establishes authorized information. The calculation applies the relevant rules to the period. The payment instruction tells the provider what to transfer. Errors can occur at any interface, even when the payroll software calculates correctly.
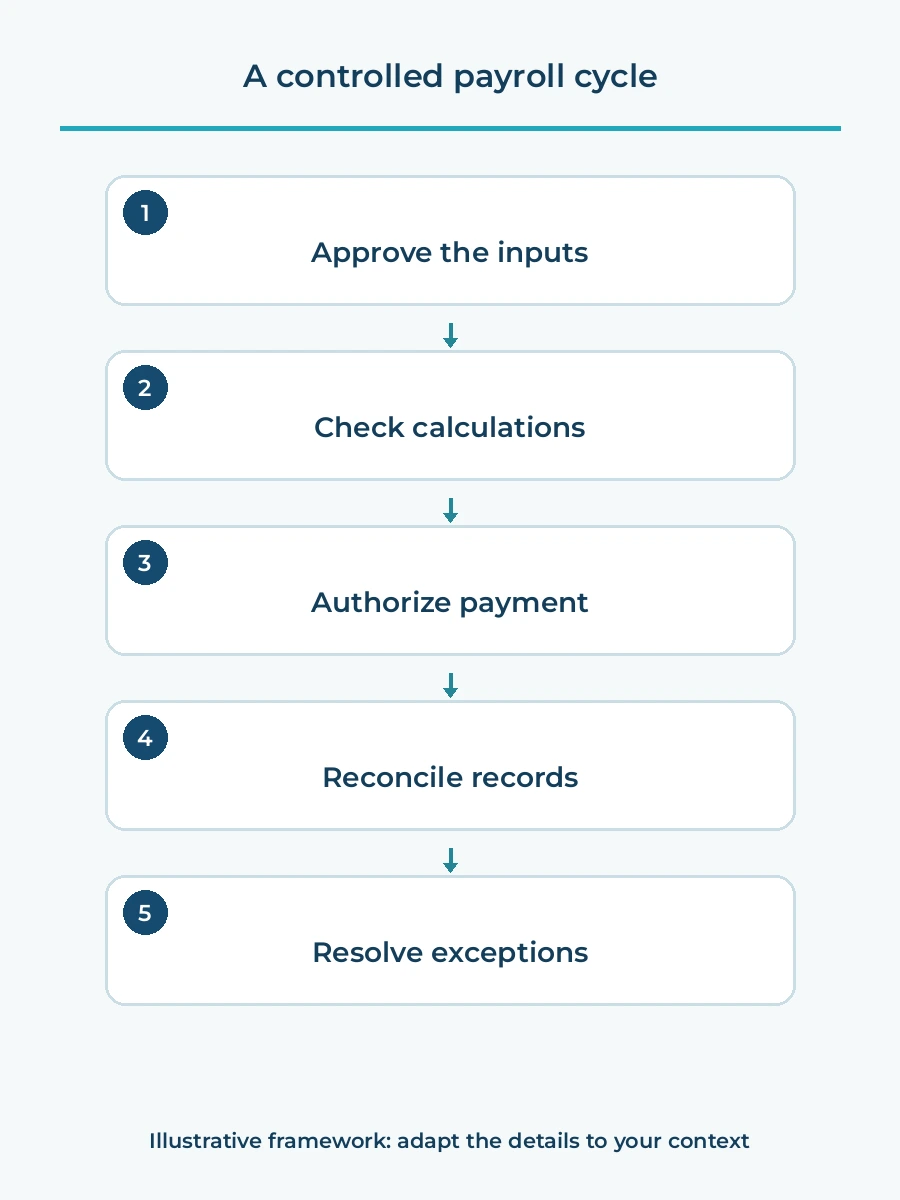
Map the process from an approved change to confirmed payment and accounting reconciliation. Include joiners, leavers, changes in compensation, variable inputs and rejected payments. These exceptions often reveal gaps that are not visible during a routine period with no changes.
Maintain controlled employee information
Define who can create or change employee master data and what approval supports each change. Important fields include employee identity, employing entity, payment details and authorized pay components. Keep an effective date so that a change is applied to the correct period.
Verify a bank-detail change through an approved process. Do not rely solely on an unexpected email asking for a different account. The person preparing payroll should be able to trace the instruction to an authorized source without receiving unnecessary personal information.
Keep access proportionate to the role. A line manager may need to approve attendance without seeing every employee's compensation. Review access when responsibilities change. Store payroll files in a controlled location and define how they are shared, retained and removed under applicable requirements.
Agree a calendar for inputs and review
Work backward from the applicable payment obligation and provider processing arrangements. Allow time for input checks, calculation, review, authorization and correction. An internal submission deadline does not replace the employer's obligations to employees.
Tell managers which inputs are required and how late changes will be handled. Record the owner of each input and the evidence supporting it. A variable payment should not enter the calculation simply because someone included it in a spreadsheet without an identifiable approval.
Maintain an exception list for missing or disputed information. Assign resolution owners and escalation routes. Do not silently treat missing information as zero or carry forward a previous value unless that treatment is appropriate, authorized and documented.
Validate the calculation and changes
Review changes from the prior period alongside the underlying transactions. Explain new employees, leavers, revised pay and unusual movements. A large difference may be legitimate, while a small repeated error may be important. Use risk-based checks rather than relying on a single percentage threshold.
| Control point | Question | Evidence |
|---|---|---|
| Employee changes | Was the change authorized and correctly dated? | Approved source record |
| Variable inputs | Does the amount match the approved period? | Input and approval trail |
| Calculation | Were the correct rules and data used? | Recalculation or focused test |
| Payment | Did the approved instruction reach the intended recipients? | Provider result and reconciliation |
Test configuration changes before using them in a live payroll. Include representative ordinary and exceptional cases. Check the effect on related components and records. A successful software update does not prove that the employer's calculation rules remain correctly configured.
Separate preparation from authorization
Where practical, have a second authorized person review the payroll before payment. The review should examine meaningful evidence, not simply confirm that a total is present. Record what was checked and how unresolved exceptions were treated.
In a small organization, full separation of duties may be difficult. Define a compensating review appropriate to the actual exposure. For example, an owner may examine changes, unusual payments and the final payment file against approved records. The review needs access to enough evidence to be effective.
Make the approved version identifiable. If a file changes after approval, reassess the affected information and obtain the required authorization again. Otherwise, a signed total may relate to a different set of payments from the one actually submitted.
Confirm payment and reconcile records
Distinguish submission from successful payment. A provider can reject particular entries or return a file for correction. Review the result, investigate failures and track each outstanding payment to resolution. Keep employees informed through appropriate private channels when a problem affects them.
Illustrative example: approved net payroll totals 100000. The provider confirms payments of 97000 and rejects entries worth 3000. The remaining 3000 is an open item to resolve, not a difference to close without explanation. Record the rejection reason, responsible owner and individual payment references. Before resubmission, check the original payment status and authorize the correction, then resubmit only rejected entries under the provider’s procedure to avoid duplicate payment. If status is uncertain, clarify it before repeating instructions.
Matching totals alone are insufficient: offsetting errors or payment to the wrong recipient can leave the total unchanged. Reconcile entry counts, amounts and recipients at employee and period level, and link each exception to evidence of its resolution.
Reconcile approved payroll, payment results and accounting entries. Explain differences rather than forcing totals to agree through an unexplained adjustment. Retain the supporting evidence according to the organization's applicable requirements and authorized retention arrangements.
Provide a clear route for employee queries. Record the issue, investigation and correction without exposing another employee's information. Repeated queries about the same component may indicate a calculation problem, an unclear explanation or a weakness in the source process.
Check local requirements explicitly
Before configuring payroll, identify the rules that apply to the employing entity and employee group. In the UAE, use the relevant authority's current guidance and obtain qualified clarification where application is uncertain. Do not copy statutory rates, deductions or deadlines from an undated article or another organization's setup.
This operational framework supports control but does not determine legal entitlement. Keep the authoritative requirement, effective date and responsible reviewer with the configuration record. Recheck affected settings when requirements or employment arrangements change.
Improve one payroll cycle at a time
Select a recent period and trace a sample of changes from approval through payment. Identify missing evidence, unclear responsibilities and recurring exceptions. Prioritize the gap most likely to cause an incorrect or delayed payment, then verify the effect of the correction in the next relevant cycle.
Read about human resources systems for the wider information flow. Business and operations modelling can help define process ownership and interfaces. A practical next step is an agreed payroll calendar and control record that connects every significant change to its authorization and payment outcome.